The United Kingdom’s gilt market is navigating a complex shift in risk appetite, driven primarily by the contagion effects emerging from its closest continental neighbour. While the Bank of England maintains its own policy trajectory, the broader European sovereign debt landscape is experiencing significant turbulence that directly impacts UK duration pricing. Investors are increasingly scrutinising the long end of the yield curve, where correlations with Eurozone peripheral bonds have tightened, suggesting that local domestic factors are no longer the sole determinant of gilt yields.
Contagion From France
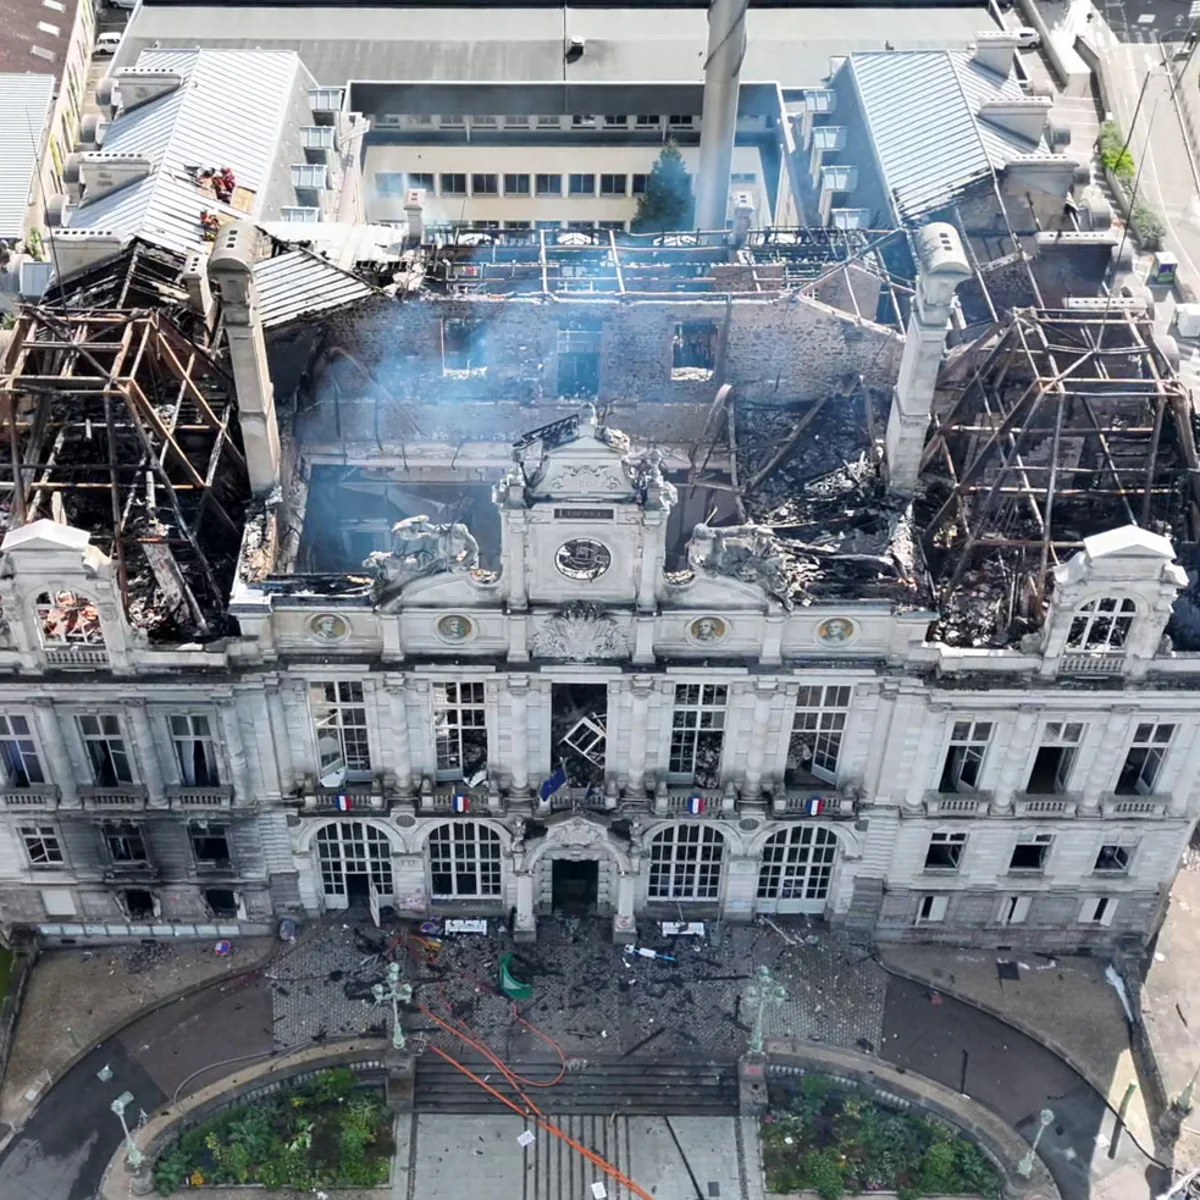
The immediate catalyst for this caution comes from France, where a fresh wave of selling in bond and stock markets has intensified following violent protests over the weekend. Reports indicate that public buildings were burned, hundreds of shops looted, and thousands of arrests occurred across the country. Such civil unrest has unnerve investors, leading to a rejection of French government debt. For UK market participants, this is a clear signal that fiscal credibility risks in the Eurozone are not being contained. The sell-off in French bonds implies a widening of credit spreads, which often acts as a leading indicator for stress in other sovereign markets, including the UK.
This external pressure complicates the domestic narrative for UK gilts. Traditionally, UK gilt yields are influenced heavily by Bank of England policy, inflation data, and fiscal announcements. However, when regional sovereign risk premiums rise, the term premium embedded in UK long-dated gilts can fluctuate independently of local fundamentals. The 'duration' of the UK debt portfolio becomes a critical variable. As investors seek safety or adjust their hedging strategies in response to Eurozone volatility, the demand for UK 30-year and 50-year gilts can become erratic, leading to sharper price movements that are not strictly correlated with UK inflation surprises.
Market structure data suggests that the AI trade unwind weighing on US and European tech equities is also contributing to a broader risk-off sentiment. When technology valuations correct, capital often rotates into defensive assets or cash, but in a period of sovereign stress, this capital may bypass traditional safe havens if they are perceived to carry political risk. This dynamic creates a feedback loop where equity volatility and sovereign stress reinforce each other, increasing the complexity of asset allocation decisions for institutional investors holding UK exposure.
Sterling Funding Implications
The knock-on effects of this environment are particularly visible in the sterling funding market. As gilt yields become more volatile due to external supply and demand shocks, the cost of hedging sterling assets denominated in other currencies adjusts accordingly. Lenders providing sterling funding to non-residents must price in the additional risk associated with gilt duration and liquidity. If the gilt market experiences sustained stress, the forward points on sterling swaps may widen, increasing the cost of borrowing in pounds for international firms and sovereign-linked entities.
Furthermore, the Bank of England’s operations are inherently linked to the stability of the gilt market. While the central bank does not directly set bonds yields, its management of liquidity and holding of government debt influences market depth. In a scenario where foreign demand for UK gilts wavers due to regional political instability, the domestic investor base—including the Bank of England and domestic pension funds—must absorb greater supply. This can lead to periods of tightness in the repo market, where the collateral value of gilts is scrutinised more closely. Traders are likely to see increased bid-ask spreads in long-dated gilts, reflecting the higher cost of providing liquidity in a stressed environment.
It is also worth noting the contrast with other asset classes. While gold has edged up slightly on diminishing expectations for US Federal Reserve rate hikes, and corporate holdings like Strategy continue to accumulate Bitcoin, these moves are specific to their respective risk premia. The gilt market, however, is tethered to the real-world political and fiscal stability of the nation. The recent protests in France serve as a stark reminder that sovereign risk is not purely economic; it is deeply political. For UK policymakers, this underscores the importance of maintaining fiscal credibility and communicating clearly about debt sustainability, as any perceived weakness in this area could be exploited by global traders reacting to Eurozone headlines.
- Monitor the spread between UK and French 10-year bonds for widening trends.
- Assess liquidity conditions in the 30-year gilt sector for increased volatility.
- Review the impact of sterling cross-currency basis trades on funding costs.
As the week progresses, the focus will remain on whether the shock from France remains isolated or begins to bleed into other parts of the G10 sovereign complex. For UK investors, the key takeaway is that duration risk is currently being priced with a geopolitical lens. The era of treating UK gilts as a purely domestic asset class is over; they are now part of a broader European risk tapestry. Consequently, portfolio managers must account for the possibility of 'noisy' price action that may not reflect changes in UK inflation or growth, but rather the political fragility of neighbouring sovereigns. This shift demands a more nuanced approach to hedging and duration management, particularly for entities with long-term liabilities funded by government debt.